
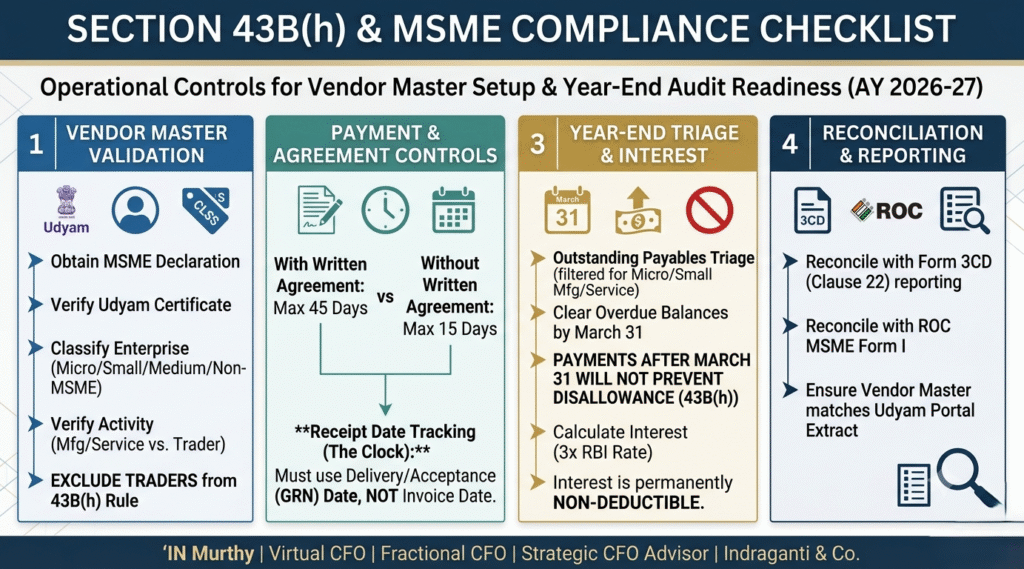
A comprehensive, high-authority operational guide and executive compliance matrix covering Section 43B(h) & MSME Compliance, detailing vendor master data governance, statutory credit period mechanics, non-deductible interest calculations, tax audit reporting under Form 3CD (Clause 22), and Registrar of Companies (ROC) reconciliation.
SECTION 43B(h) & MSME COMPLIANCE ARCHITECTURE
Vendor Master Setup, Payment Controls, Interest Mechanics & Year-End Audit Readiness,
-
Executive Statutory Overview: Section 43B(h) Mechanics
Inserted into the Income-tax Act, 1961 to enforce strict working capital discipline, Section 43B(h) dictates that any sum owed to a Micro or Small Enterprise beyond the time limit specified in Section 15 of the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006 shall be allowed as a deduction only in the previous year in which such sum is actually paid.
Key Statutory Rules:
- Non-Applicability of Proviso to Section 43B: Unlike other provisions under Section 43B (such as statutory taxes, bonus, or employer EPF contributions), settling the overdue amount after the close of the financial year (March 31) but before the Income Tax Return filing deadline under Section 139(1) will not prevent tax disallowance for that assessment year.
- Scope Restriction: The disallowance applies strictly to Micro and Small Enterprises engaged in Manufacturing or Rendering Services. Medium Enterprises and entities classified strictly as Wholesale or Retail Traders are outside the purview of Section 43B(h) disallowance.
- Year of Allowance: If an expense is disallowed in Year 1 due to late payment, it is allowed as a tax deduction in Year 2 (or the subsequent year in which the actual settlement takes place).
Vendor Onboarding Checklist:
- Mandatory Annual Vendor Declaration: Secure a signed annual declaration from every active vendor confirming their registration status under the MSMED Act, 2006.
- Udyam Registration Certificate (URC) Verification:
- Collect updated Udyam Registration Certificates for all claiming entities.
- Cross-verify the Udyam Registration Number (URN) directly on the official Government of India Udyam Verification Portal to confirm active status.
-
Enterprise Taxonomy Criteria:
- Micro Enterprise: Investment in Plant & Machinery/Equipment Less than equal to ₹2.5 Crore AND Annual Turnover less than equal to ₹10 Crore (In Scope).
- Small Enterprise: Investment in Plant & Machinery/Equipment less than equal to ₹25 Crore AND Annual Turnover less than equal too ₹100 Crore (In Scope).
- Medium Enterprise: Investment less than equal to ₹125 Crore AND Turnover less than equal to ₹500 Crore (Explicitly Exempt from Section 43B(h)).
- Non-MSME / Large Enterprise: Outside the scope of MSMED Act statutory payment limits (Exempt).
-
Activity Profile & Trader Exclusion Control:
- Manufacturing & Services: In scope for Section 43B(h) deduction rules.
- Wholesale & Retail Traders: Per Office Memorandums issued by the Ministry of MSME, trader registrations under Udyam are valid solely for Priority Sector Lending (PSL) benefits. Traders are explicitly excluded from the payment security provisions of Section 15 of the MSMED Act and Section 43B(h) of the Income-tax Act.
-
Statutory Payment Terms & The “Goods Receipt Note” (GRN) Rule
Section 15 of the MSMED Act, 2006 overrides private commercial contracts regarding maximum credit windows:
SECTION 15 CREDIT PERIOD DECISION TREE
IF
WRITTEN CONTRACT EXISTS
Agreed Credit Window
(Capped at Max 45 Days)
IF
NO WRITTEN CONTRACT
Statutory Ceiling
Strictly 15 Days
THE “CLOCK” RULE (DEEMED ACCEPTANCE)
Countdown starts from physical Delivery /
Goods Receipt Note (GRN) Date, NOT Invoice
Billing Date.
Credit Window Execution Rules:
- Written Contract Present: Payment must be executed within the mutually agreed timeframe, subject to a statutory cap of 45 days from the date of acceptance/deemed acceptance. Contractual credit clauses specifying 60, 90, or 120 days legally collapse to 45 days for Section 43B(h) tax compliance.
- No Written Contract Present: Payment must be executed within 15 days from the date of acceptance/deemed acceptance (known as the Appointed Day).
- The “Clock” Rule (GRN Date vs. Invoice Date):
- Under Section 2(b) of the MSMED Act, the credit countdown begins on the Day of Acceptance (actual physical delivery of goods or completion of services) or Day of Deemed Acceptance (where no objection is raised in writing within 15 days of delivery).
- Operational Requirement: Accounting/ERP systems must compute Section 15 due dates using the Goods Receipt Note (GRN) / Delivery Acceptance Date, rather than relying blindly on vendor invoice dates.
-
Penal Interest Calculations (Section 16 & Section 23, MSMED Act)
Failure to settle Micro or Small vendor dues within the Section 15 statutory window triggers mandatory, non-negotiable financial penalties:
- Statutory Rate & Compounding Model (Section 16)
- Mandatory Interest Rate: Compound interest at three times (3x) the Reserve Bank of India (RBI) Bank Rate.
- Compounding Frequency: Calculated with monthly rests (calendar monthly compounding).
- Overriding Status: Section 16 begins with a non-obstante clause (“Notwithstanding anything contained in any agreement…”). Any contract clause claiming “no interest on delayed payments” is legally void and unenforceable.
- Statutory Tax Disallowance of Interest (Section 23 MSMED r.w.s. 40(a)(iib))
- Interest paid or payable under Section 16 of the MSMED Act is permanently disallowed as a tax-deductible business expense under Section 23 of the MSMED Act and Section 40(a)(iib) of the Income-tax Act, 1961.
- This creates a dual tax hit: Deferred deduction of the principal amount under Section 43B(h) AND permanent tax loss on the penal interest paid.
- Year-End Closing, Cash Triage & Cross-Registry Reconciliation
Prior to closing books for the fiscal year ending March 31, the finance team must perform a comprehensive accounts payable audit and cross-reconcile reporting across tax and regulatory bodies:
March 31 Cash Triage Strategy:
- Filter the Accounts Payable ledger specifically for active Micro and Small Manufacturers/Service Providers.
- Identify all invoices where the 15-day or 45-day statutory deadline expires on or before March 31.
- Execute Priority Settlements: Fully settle these balances on or before March 31 to avoid disallowance in the current Assessment Year’s taxable income calculation.
Cross-Registry Reconciliation Matrix:
| Regulatory Body / Audit Form | Disclosure Clause | Data Requirement | Reconciliation & Audit Verification Focus |
| Tax Audit (Form 3CD) | Clause 22 | Detailed MSME Payable Ledger & Interest Schedule | Reconcile total principal disallowed under Section 43B(h) and explicit penal interest payable under Section 23 of the MSMED Act directly with the Tax Auditor’s working sheets. |
| Ministry of Corporate Affairs (MCA) | ROC MSME Form I | Half-Yearly Return of Outstanding MSME Dues | Reconcile all payables outstanding for more than 45 days reported in the half-yearly ROC MSME Form I (for periods Apr–Sep and Oct–Mar) against Clause 22 disclosures in Form 3CD to ensure zero data mismatch. |
| ERP Vendor Master File | Master Master Data Audit | Udyam Certificate Extracts & Validated Declarations | Verify that Udyam Registration Numbers, enterprise tier tags (Micro/Small/Medium), and activity flags (Trader vs. Manufacturer/Service) match official Udyam portal records. |
- Executive Compliance Checkup
- Vendor Master Classification: Are all active Micro and Small manufacturers and service providers properly flagged in your ERP with verified Udyam certificates?
- Trader Segregation: Have wholesale and retail traders been explicitly excluded from Section 43B(h) compliance workflows to protect working capital liquidity?
- GRN Date Logic: Is your accounting software calculating statutory credit expiration from the physical Delivery / GRN date instead of the vendor invoice date?
- Year-End Cash Execution: Have all Micro/Small balances breaching statutory thresholds on or before March 31 been paid in full to prevent tax additions?
- Dual Disallowance Tracking: Is penal interest under Section 16 calculated with monthly rests at 3x the RBI Bank Rate and properly added back in tax computations per Section 23?
- Are you still treating the MSME Compliance from Annual Income-Tax exercise as a Compliance arrangement or a tool for Cash & Business Management?
Let’s connect and talk.
.